How to File a Home Insurance Claim in Oregon?
Last Updated: November 6, 2026
Quick Summary
To file a home insurance claim in Oregon, first make the home safe and stop further damage, then photograph and video everything before cleaning up. Next, report the loss to your insurer promptly, get a claim number, and gather your policy, receipts, and estimates. An adjuster will then inspect the damage and estimate repair costs.
- Leave the home if there is smoke, a gas smell, or sparking wires.
- Record wide shots, close-ups, and time-stamped video before anything is repaired.
- Ask for the claim number and adjuster contact in writing after reporting.
- Check your deductible, coverage limits, and whether replacement cost or actual cash value applies.
- Keep a claim log of every call, date, and promise made by the insurer.
Table of Contents
- Step 1: Protect Yourself and Prevent Further Damage
- Step 2: Document the Damage With Photos and Video
- Step 3: Review Your Policy, Limits, and Deductible
- Step 4: Report the Home Insurance Claim and Gather Your Paperwork
- Step 5: Meet the Adjuster and Understand How Long the Claim Takes
- Common Reasons a Home Insurance Claim Is Denied or Delayed
- Reviewing Your Settlement and Next Steps for Your Home Insurance Claim
- Frequently Asked Questions
Filing a home insurance claim in Oregon can feel overwhelming when water, fire, or storm damage hits your house. The steps below will show you what to do, in order, so you stay in control. Taking the right actions in the first days after a loss makes a real difference to how smoothly your home insurance claim moves forward.
Step 1: Protect Yourself and Prevent Further Damage
Your first priority is safety. Leave the area if there is smoke, a gas smell, sparking wires, or structural risk.
Once you are safe, take reasonable steps to stop the damage from getting worse. Most policies expect you to do this, and your insurer may not pay for damage that grew because nothing was done.
- Shut off the water supply if a pipe has burst
- Turn off electricity to affected rooms if water reaches outlets
- Move valuables away from the damage
- Cover broken windows or holes with tarps or boards
- Keep receipts for any emergency repairs or supplies you buy
Save damaged items until your adjuster has seen them. Throwing things out too soon can weaken your home insurance claim.
Step 2: Document the Damage With Photos and Video
Good records are the backbone of any home insurance claim. Walk through every affected room and record it before anything is cleaned up or repaired.
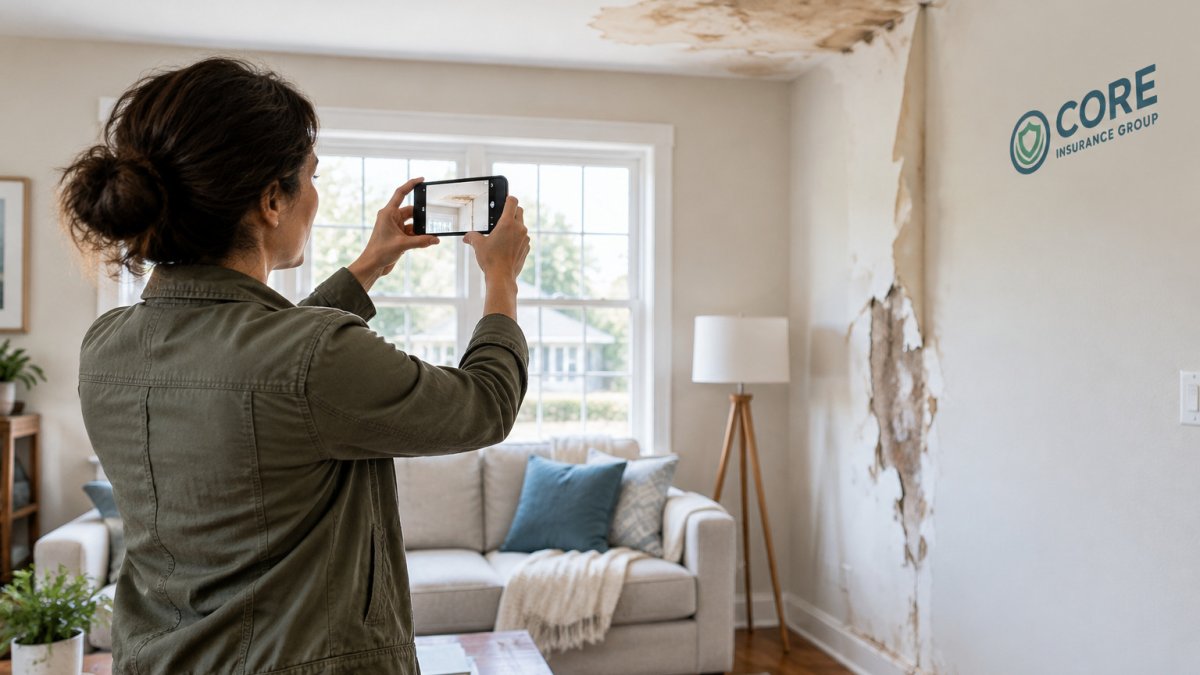
Capture these details:
- Wide shots of each room, then close-ups of specific damage
- Time-stamped video walking through the space
- Serial numbers and model numbers for damaged electronics and appliances
- Any visible cause, such as a broken pipe or a fallen tree limb
A common mistake is taking only a few photos. Record more than you think you need. Your Oregon Department of Consumer and Business Services consumer resources can also help you understand what insurers must provide during a claim.
Step 3: Review Your Policy, Limits, and Deductible
Before you call anyone, pull out your policy. Check three things: what is covered, the coverage limits, and your deductible.
Your dwelling coverage pays for the structure of your home. You can read more about how replacement cost is calculated in our guide on how to calculate home replacement cost.
Watch out: Assuming a loss is covered without checking the policy can lead to surprises later. Read the exclusions section too.
Key terms to know:
- Deductible: The amount you pay before the insurer pays its share
- Actual cash value: Replacement cost minus depreciation
- Replacement cost: The cost to repair or replace with new items of similar kind and quality
Step 4: Report the Home Insurance Claim and Gather Your Paperwork
Report the loss to your insurer or agent as soon as you reasonably can. Prompt reporting helps establish when the damage happened.
You can usually report by phone, through the insurer's app or website, or through your agent. Whichever channel you use, ask for a claim number and the name and direct line of the assigned adjuster, and write both down.
Documents to Gather Before You File
Assemble these in one folder, physical or digital, before you submit:
- Your policy declarations page and the full policy form, including endorsements
- Photos and video from Step 2, organized by room
- Receipts for emergency repairs, tarps, supplies, and any temporary housing
- A police or fire report number, if one exists
- A room-by-room inventory of damaged or lost personal property, with age, approximate purchase date, and serial or model numbers where available
Oregon Deadlines and Insurer Response Requirements
Insurers are subject to state rules for handling claims, and your policy adds its own contractual deadlines.
On the policy side, most homeowners policies require you to give prompt notice of a loss and to submit a sworn proof of loss within a set number of days after the insurer requests it.
Confirm the current state requirements directly with your insurer or the state insurance regulator, because rules and guidance can change.
Watch out: Verbal assurances from an adjuster are not a deadline extension.
A Practical Claim Timeline and Checklist
Use this as a working timeline. Exact dates depend on your policy and the insurer, so treat it as a structure rather than a guarantee.
- Day of loss: Make the home safe, stop further damage, photograph and video everything, and report the claim.
- First 24 to 72 hours: Start the property inventory, keep every receipt, and request the claim number and adjuster contact in writing.
- First week: Submit your photo and video file, the inventory so far, and contractor estimates; confirm the inspection date.
- At inspection: Walk the adjuster through every damaged area, ask for the estimate line by line, and note what was promised and when.
- After inspection: Review the estimate against your own, request any missing items in writing, and calendar every deadline the insurer sets.
Keep a simple claim log with the date, who you spoke with, and what was agreed. If a dispute arises later, that log is often the most useful document you have.
The table below summarises the key claim timeline stages covered in this section.
| Stage | What to do | Timing |
|---|---|---|
| Day of loss | Make the home safe, stop further damage, photograph everything, report the claim | Same day |
| First 24 to 72 hours | Start property inventory, keep receipts, get claim number and adjuster contact in writing | 24 to 72 hours |
| First week | Submit photos, video, inventory and contractor estimates; confirm inspection date | First week |
| At inspection | Walk adjuster through every damaged area and request line-item estimate | At inspection |
| After inspection | Review estimate, request missing items in writing, calendar every deadline | After inspection |
| Before settlement | Confirm depreciation, deductible and whether replacement cost or actual cash value applies | Before settlement |
| After settlement | Keep repair receipts and submit them if recoverable depreciation is owed | After settlement |
Step 5: Meet the Adjuster and Understand How Long the Claim Takes
An insurance adjuster will inspect the damage and estimate the cost of repairs. Be present for the inspection if you can, and point out every damaged area.
Ask the adjuster to explain the estimate line by line. Keep notes of who you spoke with, the date, and what was promised.
Timelines vary with the size of the loss, the cause, and how much documentation is provided.
Common Reasons a Home Insurance Claim Is Denied or Delayed
Claims get stuck for predictable reasons. Knowing them helps you avoid them.
- Late reporting of the loss
- Damage that came from wear, neglect, or a gradual leak
- Losses excluded by the policy, such as flood or earth movement without added coverage
- Missing documentation or receipts
- Failing to prevent further damage
If your claim is denied, ask for the denial in writing and the specific policy language it relies on.
Reviewing Your Settlement and Next Steps for Your Home Insurance Claim
When the offer arrives, read it against your own estimates and the adjuster's line-item report. Check three things first: whether the loss was valued at replacement cost or actual cash value, how depreciation was calculated, and whether your deductible was applied once and correctly.
How the Payout Is Calculated
The two valuation methods produce very different checks:
- Actual cash value (ACV): replacement cost minus depreciation. Older items pay out less because age and wear are subtracted.
- Replacement cost (RCV): the cost to repair or replace with new items of similar kind and quality, without subtracting depreciation.
Many replacement-cost policies pay in two stages. The insurer first pays the actual cash value, then releases the withheld depreciation, often called recoverable depreciation, after you complete the repairs and submit receipts and documentation. That means your first check may be smaller than the final cost, and you may need to cover the gap until the second payment arrives.
A simple way to see it: if a covered repair is valued at replacement cost and depreciation is withheld, your first payment reflects the depreciated figure, and the remainder is released once the work is done and documented. Your out-of-pocket exposure in the meantime is the difference plus your deductible.
Additional Living Expenses and Temporary Housing
If your home is uninhabitable, loss-of-use coverage may pay for temporary housing, meals above your normal cost, and related expenses, up to the limit in your policy. Document everything: hotel and rental receipts, mileage, laundry, and pet boarding. Ask the insurer in writing what the limit is, how long it applies, and what documentation it requires, and confirm whether the limit is a dollar cap or a time cap.
If the Offer Is Low, Delayed, or Denied
You have a clear escalation path. Work through it in order and keep everything in writing.
- Request a written explanation. Ask the adjuster or claims supervisor to identify the specific policy language and estimate lines behind the decision.
- Submit your own evidence. Send contractor estimates, additional photos, and receipts for items the estimate missed, and ask for a re-review.
- Escalate internally. Ask for a supervisor or the insurer's formal appeal or complaint process, and put the request in writing.
- Contact the regulator. The State insurance regulators accept consumer complaints about claim handling (Division of Financial Regulation ). Filing a complaint does not replace your policy rights, but it creates an independent record.
- Consider professional help. For large or disputed claims, a public adjuster or an attorney may be worth consulting. Confirm fees and licensing before you sign anything.
Watch out: cashing a settlement check can, depending on the language you signed, be treated as acceptance of the offer. If you dispute the amount, ask the insurer in writing how to preserve your rights before depositing it.
Next Steps
- Keep every document, receipt, and claim-log entry in one folder
- Make permanent repairs only after the adjuster has approved them, unless safety requires immediate action
- Track the recoverable depreciation you are owed and submit receipts as repairs finish
- Calendar follow-up dates so delays do not quietly become denials
Core Insurance Group offers personalized guidance through every stage of a home claim, with a commitment to clear, transparent service. Contact us today to review your coverage or get a quote, and let us help you move forward with confidence.
Frequently Asked Questions
What should I do first when filing a homeowners insurance claim?
First make sure everyone is safe, then take reasonable steps to prevent further damage, such as covering a broken window or shutting off water. Keep receipts for any emergency repairs. Next, document the damage with dated photos and video, and contact your insurer to report the loss. Ask for a claim number and write down the name of the representative you speak with, along with the date and time of the call.
What information and documents do I need to file a home insurance claim?
Have your policy number, the date and cause of the loss, and a description of the damage ready. Gather photos and video, a home inventory listing damaged or lost personal property with approximate purchase dates and values, receipts, repair estimates, and a police or fire report if one exists. Keep copies of everything you send and receive, so you can support your proof of loss if the insurer asks for it.
What are common reasons a home insurance claim may be denied?
Claims are often denied or reduced when the loss falls under an exclusion, such as wear and tear, gradual leaks, or flood damage that requires separate coverage. Late reporting, failure to mitigate further damage, and incomplete documentation are also frequent problems. Reading your policy's coverage limits and deductible before filing helps you understand what to expect and gives you a basis for a written appeal if a decision seems wrong.
How long does a home insurance claim usually take?
Timelines vary with the size of the loss, the complexity of the damage, and how quickly you supply documentation. Keeping a written log of every contact and following up in writing when you have not heard back are practical ways to keep the claim moving.

Want this checked against your own policy?
We compare 100+ carriers and tell you what actually changes.